Published September 14, 2026
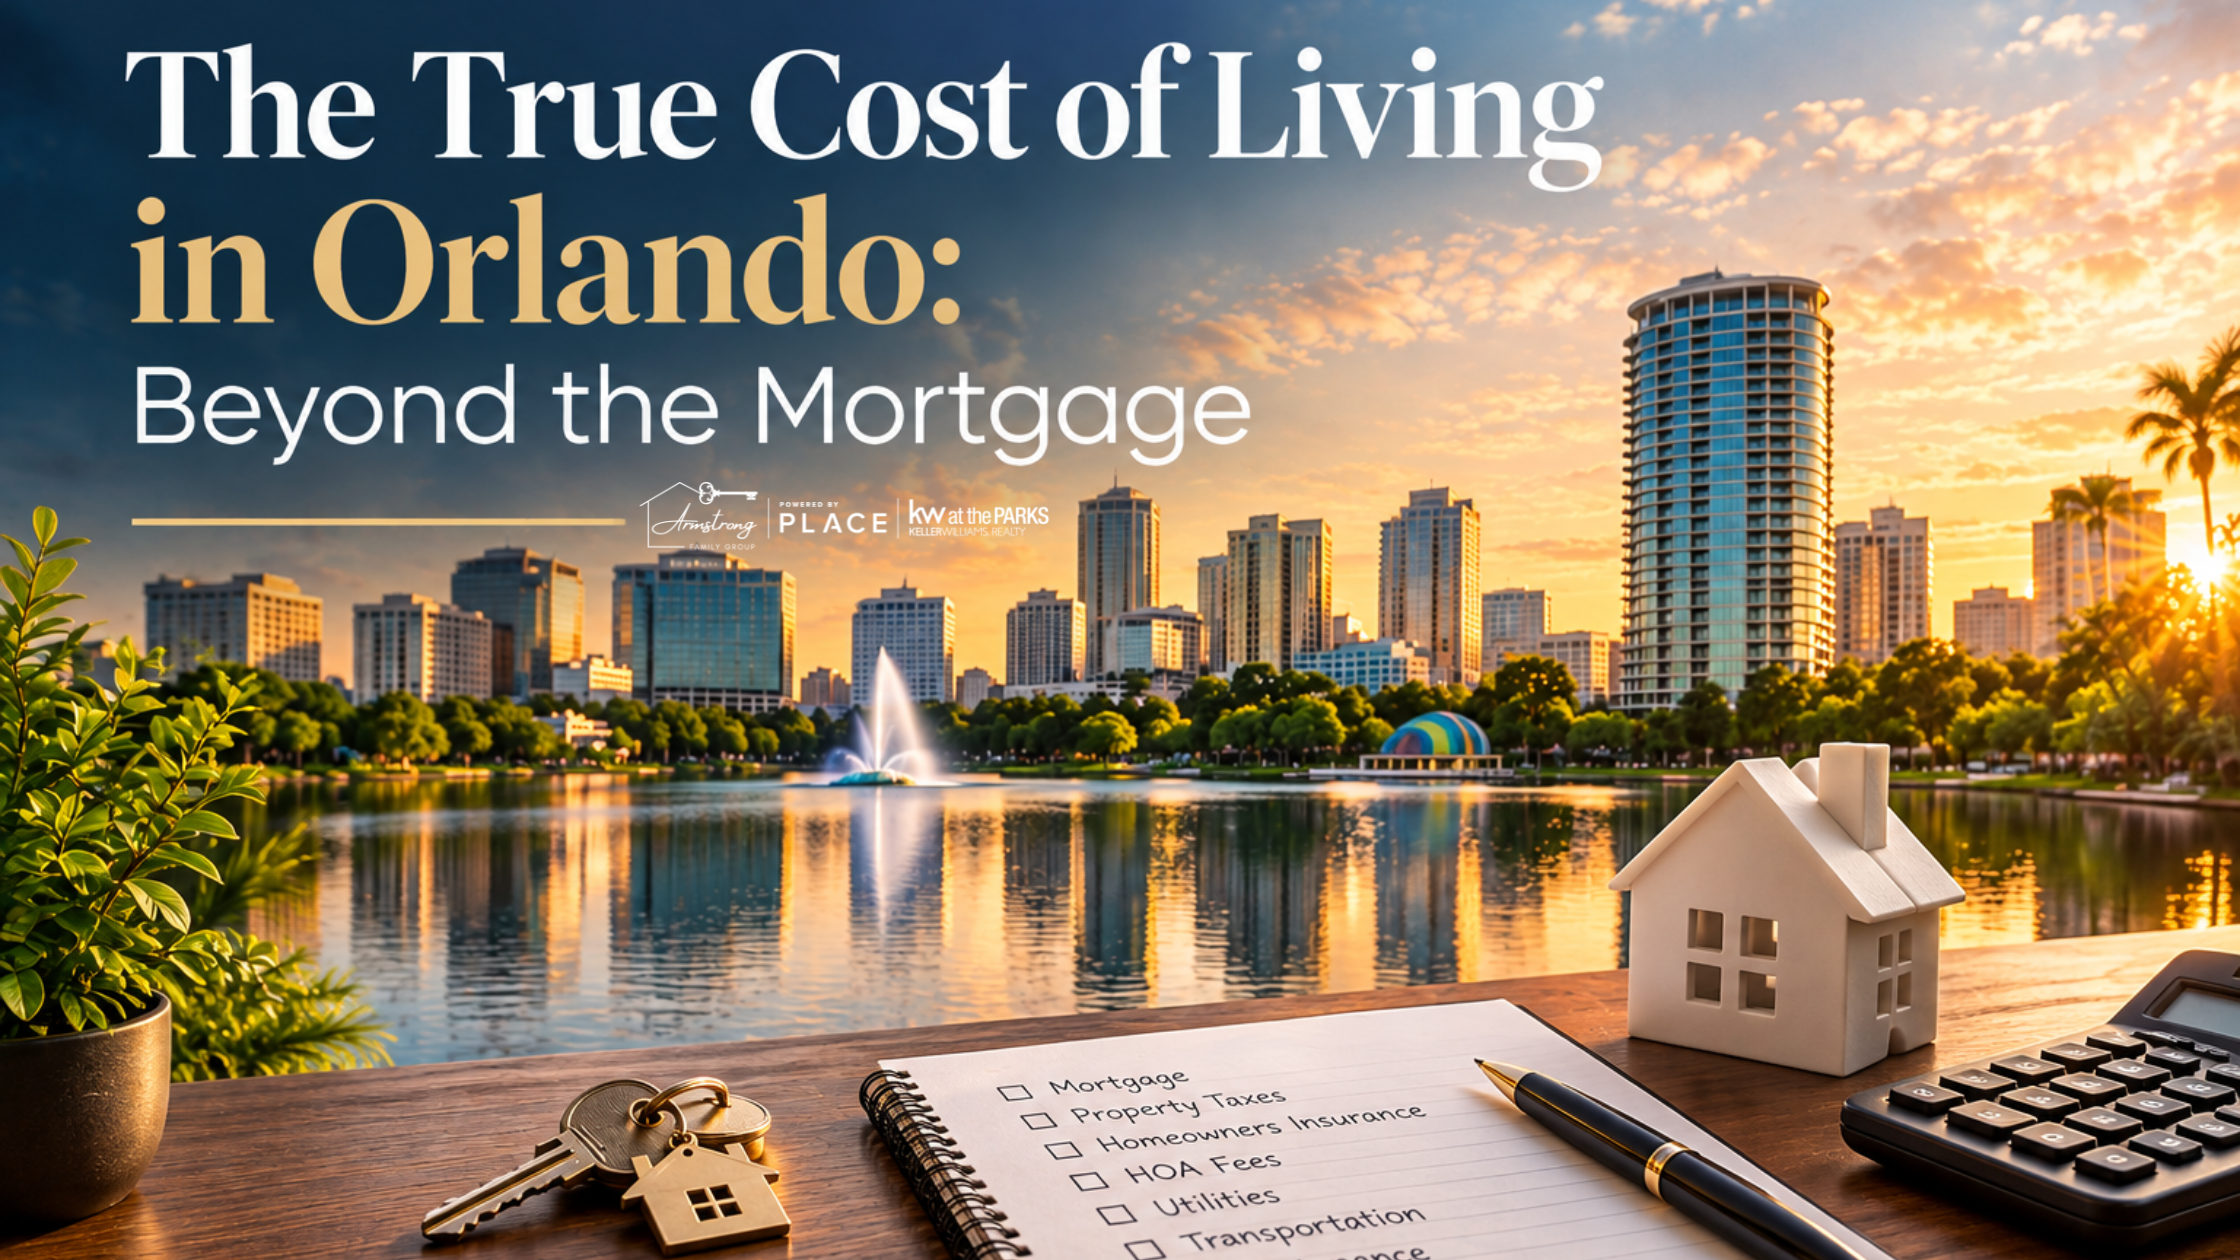
The True Cost of Living in Orlando: Beyond the Mortgage
Thinking about buying a home in Orlando? It’s easy to focus on one number: the mortgage payment.
But your monthly housing payment is only one piece of the puzzle.
Whether you're moving to Orlando from another state, relocating within Florida, or simply trying to understand what it really costs to live here, there are several expenses you should consider before making a move.
From property taxes and homeowners insurance to utilities, transportation, and HOA fees, understanding the full cost of living can help you make a smarter homebuying decision.
1. Your Mortgage Is Only the Beginning
When estimating your monthly housing costs, don't stop at principal and interest.
Depending on the property, your monthly payment may also include:
- Property taxes
- Homeowners insurance
- Flood insurance, if required or desired
- HOA or community fees
- Mortgage insurance, depending on your loan
- Maintenance and repairs
Two homes with the same purchase price can have very different monthly costs depending on their location, insurance requirements, taxes, and community fees.
That's why we recommend looking at the total monthly cost of owning a home, rather than simply comparing listing prices.
2. Property Taxes in Orlando
Florida does not have a state individual income tax, which is one reason the state continues to attract people relocating from higher-tax states.
However, homeowners still need to budget for property taxes.
Your property tax bill depends on factors including:
- The property's assessed value
- Local millage rates
- Your eligibility for exemptions
- The property's location
For Florida homeowners, the Homestead Exemption can be especially important if the property will be your primary residence.
If you're purchasing a home, don't assume that the current owner's tax bill will automatically be your future tax bill. A change in ownership can affect the property's assessed value and future taxes.
3. Homeowners Insurance Can Be a Major Expense
Insurance is an important part of the Florida homeownership equation.
Premiums can vary significantly depending on the home's age, roof, construction, location, coverage, deductible, and other factors.
Before purchasing a home, it's smart to get an insurance quote rather than simply estimating the cost.
A home that looks affordable based on the mortgage alone may have a very different monthly cost once insurance is included.
Tip: Ask your Realtor and insurance professional about the property's insurance history and get quotes early in the buying process.
4. HOA Fees Can Change Your Monthly Budget
Many Orlando-area communities have homeowners associations.
Depending on the neighborhood and property type, an HOA may cover things such as:
- Community amenities
- Landscaping
- Common-area maintenance
- Gated-entry services
- Exterior maintenance in some communities
- Recreational facilities
HOA fees can range from relatively modest amounts to several hundred dollars per month or more.
If you're comparing two homes, don't look only at their prices. Compare their total monthly ownership costs, including HOA fees.
5. Utilities: Electricity, Water & Internet
Florida's climate means air conditioning is not exactly optional.
Electricity can therefore become one of the larger household utility expenses, particularly during Orlando's hotter months.
Your utility costs will depend on factors such as:
- Home size
- Energy efficiency
- Age of the HVAC system
- Thermostat settings
- Number of occupants
- Pool equipment
- Insulation and windows
Other recurring expenses can include water, sewer, trash service, internet, and mobile services.
When touring a home, it's worth asking about the age and condition of the HVAC system and other major systems that can influence future utility and maintenance costs.
6. Transportation Is Part of the Housing Decision
Where you live in Orlando can have a major impact on your transportation costs.
Orlando is a large and spread-out metro area, and many residents rely on their vehicles for commuting, shopping, school, and everyday activities.
That means your real housing budget should consider:
- Car payments
- Auto insurance
- Gas
- Maintenance
- Parking
- Tolls
- Daily commute
A home that costs slightly more but significantly reduces your daily commute could potentially make more sense financially and personally than a less expensive home farther away.
Don't just ask, "What can I afford?" Ask, "What will my lifestyle cost here?"
7. Maintenance and Repairs
One of the biggest differences between renting and owning is responsibility for maintenance.
As a homeowner, you may eventually need to budget for:
- HVAC repairs or replacement
- Roof maintenance
- Plumbing
- Appliances
- Landscaping
- Pest control
- Exterior maintenance
- Unexpected repairs
There isn't one perfect number for how much you should set aside, but having an emergency fund specifically for homeownership can help prevent an unexpected repair from becoming a financial crisis.
8. The Cost of Living Depends on Your Lifestyle
There isn't one universal "cost of living in Orlando."
A young professional living in a condo downtown may have a completely different budget from a family living in a larger home in the suburbs.
Your expenses can change significantly based on:
- Where you live
- Home size
- Number of household members
- Commute
- Dining and entertainment
- Childcare
- Schooling
- Insurance
- Lifestyle choices
That's why national cost-of-living calculators don't always tell the complete story.
9. Don't Forget the Upfront Costs of Buying
Your monthly payment isn't the only expense you'll encounter when purchasing a home.
Buyers should also plan for upfront costs such as:
- Down payment
- Closing costs
- Inspection
- Appraisal
- Moving expenses
- Initial repairs or improvements
- Furniture and appliances
The exact amount you'll need depends on your loan program, purchase price, negotiations, and other factors.
A good lender can help you understand your estimated cash-to-close before you start making offers.
10. So, Is Orlando Still Affordable?
The answer depends on what you're comparing it to and what you're looking for.
Orlando has experienced significant growth, and housing costs have changed over the years. At the same time, Florida's lack of a state individual income tax remains an important consideration for many people relocating from other states.
The key is to look beyond the listing price.
A $450,000 home isn't really a $450,000 decision.
It's a decision about your mortgage, taxes, insurance, utilities, transportation, maintenance, HOA fees, lifestyle, and long-term financial goals.
The Bottom Line
If you're considering buying a home in Orlando, don't build your budget around the mortgage alone.
Before making a decision, look at the full cost of homeownership and ask yourself:
What will this home actually cost me every month?
That's the number that matters.
And if you're relocating to Orlando, understanding those costs before you start shopping can help you choose a neighborhood and home that fit not only your budget—but your lifestyle.
Thinking About Buying in Orlando?
Whether you're a first-time buyer, relocating to Central Florida, or looking for your next home, having a local real estate team by your side can make the process easier.
Armstrong Family Group can help you understand the local market, compare neighborhoods, and connect the pieces between your budget and the home you want.
Ready to explore your Orlando options? Let's start the conversation.